The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
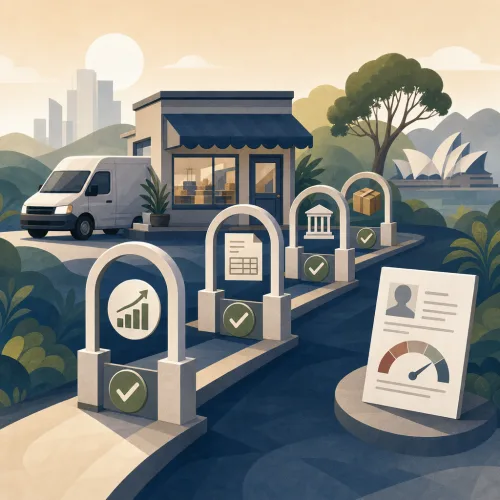
Business loans without a traditional credit check are usually assessed through cash flow, trading data, invoices, bank statements, security and business viability rather than relying only on a credit score.
For many Australian small business owners, sole traders and self-employed borrowers, a traditional credit check does not always tell the full story. A director may have an old default, limited personal credit history, irregular income or a business that is growing faster than its financial records suggest.
Business loans without a traditional credit check are not usually loans with no assessment at all. In practice, they often mean the lender does not rely mainly on a standard personal credit score or credit file when deciding whether to offer finance. Instead, the lender may look more closely at business cash flow, recent trading activity, bank statements, invoices, assets, contracts, tax records and the purpose of the loan.
This guide explains how business loan assessment may work in Australia when credit history is poor, limited or complex. It is general information only and does not take your objectives, financial situation or needs into account.
What does "without a traditional credit check" usually mean?
The phrase can mean different things depending on the lender, broker or finance product. It is important to read the wording carefully before applying.
In a business finance context, "without a traditional credit check" may mean:
- the lender places less weight on your personal credit score than a bank might;
- the lender uses bank statement data, sales records or accounting information as the main assessment tool;
- the product is secured by an asset, invoice, equipment or other business-related collateral;
- the lender considers recent business performance more heavily than older credit issues;
- the lender conducts a soft or preliminary assessment before any formal application; or
- a broker reviews your circumstances before matching you with possible lenders.
It does not necessarily mean your credit file will never be checked. Some lenders may still review the credit history of the business, directors, guarantors or related entities, especially before issuing final approval or where a personal guarantee is required. Others may check for fraud, identity verification, insolvency information or serious repayment problems.
If you are comparing business funding pathways, ask each provider what type of assessment they use, whether they perform a credit enquiry, and at what stage that enquiry occurs.
How business loan assessment can work without relying mainly on a credit score
When a lender does not rely mainly on a traditional credit check, the assessment generally shifts toward the business's ability to repay. The lender wants to understand whether the business has enough reliable cash flow to meet repayments after normal operating expenses.
Common assessment factors may include:
- Recent revenue: how much money has been coming into the business bank account over recent months.
- Cash flow consistency: whether income is regular, seasonal, lumpy or dependent on a small number of customers.
- Trading history: how long the business has held an ABN, been operating and generated revenue.
- Bank account conduct: whether the account shows unpaid direct debits, dishonours, overdraft pressure or frequent shortfalls.
- Existing debts: current loans, tax payment plans, equipment finance, credit cards, supplier debts and other commitments.
- Purpose of funds: whether the loan is for stock, equipment, cash flow, expansion, tax obligations, wages, marketing or another business purpose.
- Security or guarantees: whether the lender requires an asset, personal guarantee, director guarantee or other form of support.
- Industry and business model: how the business earns income and whether the loan purpose aligns with its operations.
This type of business loan assessment can suit borrowers whose credit history is not straightforward, but it is still an assessment. Lenders set their own criteria, and outcomes depend on the individual business, the loan type, the amount requested and the lender's risk appetite.
Documents and business data lenders may ask for
Document requirements vary, but business lenders commonly ask for information that helps them verify income, expenses and trading activity. A document-based approach can be especially important for bad credit business loans, unsecured business loans Australia-wide and other forms of small business finance bad credit borrowers may consider.
You may be asked for:
- ABN and business registration details;
- identification for directors, owners or guarantors;
- business bank statements;
- BAS or GST records, where applicable;
- recent profit and loss information or management accounts;
- invoices, debtor reports or contracts;
- merchant sales or payment platform data;
- details of existing loans, leases or finance agreements;
- ATO payment plan information, if relevant;
- asset details for secured or equipment-backed finance; and
- an explanation of past credit issues or unusual account activity.
Some borrowers use brokers to help organise documents and identify lenders that may consider cash flow, invoices, assets or trading performance rather than focusing only on a traditional credit score. A broker's involvement does not ensure approval, and you should still understand any fees, commissions, lender criteria and loan terms before proceeding.
Types of business finance that may use alternative assessment
There is no single product called a "business loan without a traditional credit check". Different finance structures may use different assessment methods. The right structure depends on the business purpose, repayment capacity, available security and provider criteria.
| Finance type | How assessment may work | Key points to check |
|---|
| Unsecured business loan | Lender may review bank statements, revenue, trading history and existing commitments. | Rates, fees, repayment frequency, personal guarantees and default consequences. |
| Secured business loan | Assessment may include the value and type of security as well as business cash flow. | What asset is at risk, valuation assumptions, enforcement rights and total cost. |
| Equipment or asset finance | The equipment or vehicle being financed may support the loan, alongside business affordability. | Ownership structure, balloon or residual amounts, early payout costs and asset use restrictions. |
| Invoice finance | Lender may focus on unpaid invoices, customer quality and debtor collection patterns. | Advance rates, fees, recourse arrangements, customer notification and cash flow timing. |
| Merchant or revenue-based finance | Assessment may use card sales, platform revenue or daily trading data. | Repayment method, impact on daily cash flow, fees and what happens if sales fall. |
| Business line of credit | Lender may assess revenue, account conduct and ability to manage revolving debt. | Drawdown fees, limits, interest calculation, review rights and discipline around reuse. |
These products can differ significantly. A finance option that suits a seasonal retailer may not suit a contractor, café, transport operator or professional services business. Always compare total cost, repayment timing and the consequences of missed payments, not just the headline amount available.
Why lenders may look beyond personal credit history
Small business borrowing often involves factors that do not appear clearly in a personal credit report. A sole trader may have strong current sales but a past personal default. A company director may have limited consumer credit activity but reliable business revenue. A contractor may have irregular deposits but signed contracts that support future income.
Alternative assessment can help a lender understand:
- whether the business has recovered from earlier financial difficulty;
- whether recent cash flow supports the proposed repayments;
- whether the borrowing purpose is connected to business growth or stability;
- whether seasonal trading patterns explain uneven income;
- whether security or invoices reduce the lender's risk; and
- whether the requested loan amount is proportionate to turnover and margins.
However, poor credit history can still matter. Recent defaults, unpaid tax debts, insolvency events, repeated dishonours or heavy existing debt may affect eligibility, pricing or the amount offered. Some lenders may decline an application even if they use non-traditional assessment methods.
How to strengthen a business loan application when credit is imperfect
If your credit file is poor, thin or complicated, the aim is to make the business case clear and verifiable. You may not be able to change historical credit issues quickly, but you can often improve the quality of the information supplied.
Prepare a clear loan purpose
Be specific about why the business needs the funds. "Working capital" is broad; "buying stock for confirmed seasonal orders" or "replacing a key vehicle used for deliveries" gives the lender more context. The purpose should be realistic and connected to business operations.
Organise recent financial records
Clean, complete records help reduce uncertainty. Make sure bank statements, BAS, invoices, debtor lists and management accounts are consistent. If there are unusual transactions, be ready to explain them.
Check repayment capacity before applying
Work out whether the business can handle repayments in a normal month and a weaker month. Consider wages, rent, supplier payments, tax obligations, insurance, existing debts and seasonal cash flow. You can use available loan calculators to test repayment scenarios before deciding whether a proposed loan size or term looks manageable.
Limit unnecessary applications
Submitting multiple formal applications in a short period can create avoidable pressure and may affect how some lenders view the business. Before applying, ask whether the provider can conduct an initial eligibility discussion or soft assessment, and whether a formal credit enquiry will be made.
Explain credit issues honestly
If there was a specific reason for past credit trouble, such as a temporary downturn, client non-payment or personal event, provide a concise explanation and evidence of recovery where possible. Avoid hiding relevant information, as inconsistencies can damage confidence in the application.
For broader preparation tips, see our guide on improving loan approval odds without affecting credit. While that article is consumer-focused, many principles such as preparing accurate information and checking affordability are also relevant to business borrowers.
Costs and risks to review carefully
Business finance that relies less on traditional credit scoring may carry higher costs, shorter terms, more frequent repayments or additional security requirements. This is not always the case, but it is common for lenders to price for higher perceived risk.
Before accepting an offer, review:
- Total repayment amount: the full amount payable over the life of the loan, including fees.
- Repayment frequency: daily, weekly, fortnightly or monthly repayments can affect cash flow differently.
- Upfront and ongoing fees: application, establishment, account-keeping, broker, early repayment or default fees may apply.
- Security interests: secured loans may involve claims over vehicles, equipment, invoices or other business assets.
- Personal or director guarantees: these can expose personal assets or income if the business cannot repay.
- Default terms: check what happens if a repayment is missed or sales decline.
- Early payout rules: some products may not reduce the cost as much as expected if repaid early.
- Business-purpose declaration: ensure the loan purpose is accurate and that you understand the contract you are signing.
Consider getting independent legal, accounting or financial advice if the loan is large, secured, personally guaranteed or difficult to understand. This is especially important where business and personal finances are closely linked.
Warning signs to take seriously
Urgent funding needs can make borrowers vulnerable to poor decisions. Be cautious if a provider:
- suggests approval is certain before reviewing your business information;
- will not clearly explain fees, repayments or the total cost;
- pressures you to sign immediately;
- asks you to misstate the loan purpose or income;
- avoids explaining whether a credit enquiry will occur;
- does not provide clear contract documents;
- encourages borrowing more than the business can reasonably repay; or
- downplays the effect of personal guarantees or secured assets.
A reputable process should allow you to ask questions, compare terms and understand your obligations before you commit.
Questions to ask before applying
Before submitting a business loan application, ask the lender or broker:
- Will you check my personal credit file, business credit file or both?
- Is the initial assessment a soft check, document review or formal application?
- What business bank statements, BAS, invoices or accounting records do you need?
- How do you assess seasonal or irregular cash flow?
- Will I need to provide security or a personal guarantee?
- What is the total cost of the loan, including fees?
- How often are repayments made?
- What happens if revenue drops temporarily?
- Can I repay early, and how is the payout figure calculated?
- Will applying affect my credit file?
The answers can help you decide whether the finance option is suitable for further consideration and whether the lender's assessment style matches your circumstances.
Key takeaway
Business loans no credit check Australia searches often come from borrowers who are worried that a traditional credit score will stop them from accessing finance. In reality, many business lenders still assess risk carefully, but some may place more weight on trading performance, bank statements, invoices, assets and cash flow than on a standard credit score alone.
For Australian small business owners with bad credit, limited credit history or complex income, the most useful approach is to prepare clear documents, understand the repayment impact and ask direct questions about how the application will be assessed. A loan should support the business, not create repayment pressure that makes trading harder.
Published: Sunday, 2nd Aug 2026
Author: Paige Estritori





No comments yet. Be the first to share your thoughts.