No Credit Check :: Articles

Denied a Loan Due to Your Credit Score? What to Do Next

What should you do first if your loan application is denied due to a low credit score?

Denied a Loan Due to Your Credit Score? What to Do Next

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Being declined for a loan because of your credit score can be frustrating, but it can also give you useful information. By reviewing the reason for the decision, checking your credit report and improving the factors lenders assess, you can be better prepared before considering another application.

If your loan application is declined because of your credit score

A credit score is one way lenders assess how likely a borrower is to repay money they borrow. If a lender declines your application because of your credit score, it does not mean you have no options, but it does mean you should pause before applying again.

Repeated credit applications can create additional enquiries on your credit file. Instead of immediately submitting another application, it is usually more useful to understand why the application was declined, check whether your credit report is accurate and address the factors that may have affected the lender's decision.

How credit scores affect loan approval

A credit score is a numerical representation of creditworthiness based on information in your credit history. In Australia, some credit scoring models use a scale that can run from 0 to 1,200. The score may be influenced by factors such as repayment history, existing debts, the length of your credit history and recent credit applications.

Lenders use credit scores and credit reports to help assess risk. A higher score may support an application, while a lower score may limit available options or lead to higher borrowing costs. However, a credit score is not the only factor a lender may consider. Income, expenses, existing commitments, loan type and the lender's own criteria can also matter.

Credit score rangeHow it is commonly describedPossible lending impact
Above 800ExcellentMay support access to stronger loan terms, depending on the lender and application details.
700 to 799GoodMay be viewed favourably by many lenders, subject to other assessment criteria.
500 to 699FairMay reduce the number of suitable loan options or affect pricing.
Below 500PoorMay make approval more difficult and can increase borrowing costs where finance is available.

Different loan types may also treat credit score information differently. Personal loans often rely heavily on creditworthiness. Mortgages may involve more stringent assessment. Car loans may be assessed differently again, depending on the lender, the borrower and whether the loan is secured.

Steps to take after a loan denial

  1. Review the lender's explanation. Start with any denial notice or explanation you receive. It may identify whether the issue related to your credit score, repayment history, existing debt, income, affordability or another factor.
  2. Ask the lender for more detail. If the explanation is unclear, contact the lender and ask which parts of the application affected the outcome. Understanding the lender's criteria can help you decide what to address before applying elsewhere.
  3. Get a copy of your credit report. In Australia, you can request a free credit report each year from the main credit reporting agencies: Equifax, Experian and illion. Reviewing your report helps you see what lenders may be seeing.
  4. Check for incorrect information. Look for errors such as incorrect personal details, accounts you do not recognise, wrongly recorded missed payments or outdated information.
  5. Dispute errors promptly. If you find inaccurate information, follow the relevant credit reporting agency's dispute process. Correcting errors can help ensure your report accurately reflects your credit history.

How to improve your credit score before applying again

Pay bills and loan repayments on time

Payment history is an important part of credit assessment. Paying bills, credit cards and loan repayments on time can help protect your credit profile. Reminders or automated payments may help reduce the risk of missed due dates.

Reduce existing debt where possible

Existing debts can affect both your credit score and a lender's view of affordability. Reducing balances, particularly high credit card balances, may improve your position over time. The original article suggested aiming to use less than 30% of available credit limits as a practical benchmark.

Keep credit card balances manageable

High credit card balances can weigh against your credit profile. Paying balances down, and paying them in full where possible, may help show responsible credit management.

Limit unnecessary new credit applications

Each application for credit may result in a credit enquiry. Multiple enquiries in a short period can make an application look riskier to some lenders. If you are not ready to apply, consider researching criteria and checking your credit report first.

Don't forget the insurance!

Insurance Online logo Insurance Online is an Australian online insurance resource with articles, guides, calculators and news on personal and business cover. Enquiries are referred to licensed brokers from a national partner network who can discuss your needs and compare options.

Monitor your credit report

Regularly checking your credit report can help you identify errors or negative marks that need attention. It can also help you understand whether your credit habits are moving in the right direction.

Consider the affordability of any future loan

Before applying again, it can be useful to estimate repayments under different loan amounts and terms. A personal loan repayment calculator can help you understand how repayments may fit into a budget, although it does not determine whether a lender will approve an application.

Thinking about another loan application

Once you understand why the application was declined, you can decide whether it makes sense to apply again immediately or spend time improving your credit position first. If your credit report contains errors, resolve them before submitting another application. If the issue is missed payments or high balances, improvement may take time and consistency.

If you want to research options without creating unnecessary credit enquiries, learn how soft credit checks may be used when comparing some loan options. Soft checks are different from formal hard enquiries, but borrowers should still read each lender's process carefully.

If you decide to compare available personal loan options, focus on the full terms, fees, repayment schedule and eligibility criteria rather than only the advertised rate or speed of application.

Alternative loan options to understand

If a traditional loan is declined because of your credit score, there may be other types of lending to consider. These options can involve different costs, criteria and risks, so it is important to understand how each works before applying.

Secured loans

A secured loan requires collateral, such as a car or another eligible asset. Because the loan is supported by collateral, the lender's risk may be lower than with an unsecured loan. This can affect how the application is assessed, but approval is not guaranteed.

Unsecured loans

An unsecured loan does not require collateral. The lender relies more heavily on creditworthiness, income, expenses and repayment capacity. If your credit score is low, unsecured loans may be harder to access or may involve higher borrowing costs.

Credit unions and community banks

Credit unions and community banks may apply different lending criteria from larger institutions. If you already have a relationship with one, it may be worth asking how they assess applications from borrowers with weaker credit histories.

Online lenders

Online lenders can offer digital application processes and faster decisions. Some focus on borrowers with less-than-perfect credit, but terms can vary widely. Read the loan contract, fees, interest rate and repayment requirements before proceeding.

Peer-to-peer lending

Peer-to-peer lending platforms connect borrowers with individual investors who fund loans. Criteria and pricing can differ from traditional lenders. As with any borrowing option, review the terms carefully and consider whether repayments are manageable.

No-credit-check style assessments

Some borrowers look for lenders that assess applications without relying only on a traditional credit score. These products still involve assessment and may consider other information about income, expenses and repayment capacity. You can read more about no-credit-check loan assessments before deciding whether this type of option is relevant to your situation.

Longer-term credit habits

Improving a credit score usually takes time. The most useful habits are consistent: pay obligations on time, reduce unnecessary debt, keep credit card balances under control, avoid repeated credit applications and check your credit report for accuracy.

A loan denial can feel discouraging, but it can also highlight what to improve before you approach another lender. Taking time to understand the reason for the decline and strengthen your credit profile may put you in a better position for future credit decisions, without guaranteeing any particular outcome.

Published: Tuesday, 18th Mar 2025
Author: Paige Estritori

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.


Finance Articles

Budgeting Basics to Keep Your Credit Score Healthy While Seeking a Loan
Understanding the nuances of financial health is a crucial component in the journey of loan acquisition. It is the bedrock on which potential borrowers build their case for credibility and reliability. Among the myriad of factors influencing your fiscal stability, credit scores stand out as a beacon indicating your creditworthiness to lenders. A robust credit score simplifies the path to securing loans, garnering favorable interest rates, and negotiating better terms. - read more
How Your Credit Score Affects Loan Approval and Interest Rates
Your credit score is a crucial part of your financial health. Essentially, it’s a numerical representation of your creditworthiness, calculated based on your credit history. In Australia, credit scores range from 0 to 1200, with a higher score indicating better creditworthiness. - read more
Soft Credit Checks: How to Compare Loans Without Unnecessary Credit Score Impact
Soft credit checks can help you explore loan options without adding unnecessary pressure to your credit score. Understanding the difference between soft and hard credit enquiries can make it easier to compare lenders, review repayment scenarios and decide when a formal application is worth making. - read more
How to Use Loan Comparison Tools Effectively - A Guide for the Credit-Conscious
When it comes to securing a loan, the terms you agree to can have a lasting impact on your financial wellness. It's crucial to strike a balance between finding a loan that fits your needs and maintaining a healthy credit score. This delicate equilibrium is where loan comparison tools come into play, serving as navigational aids in the vast sea of credit options. - read more
Business Loans Without a Traditional Credit Check: What Australian Borrowers Should Know
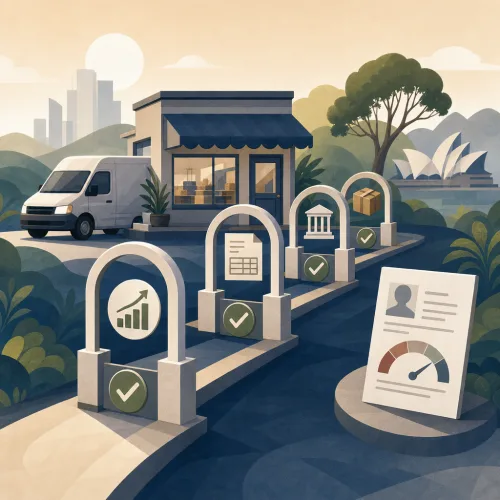
Business loans without a traditional credit check are usually assessed through cash flow, trading data, invoices, bank statements, security and business viability rather than relying only on a credit score. - read more
Denied a Loan Due to Your Credit Score? What to Do Next
Being declined for a loan because of your credit score can be frustrating, but it can also give you useful information. By reviewing the reason for the decision, checking your credit report and improving the factors lenders assess, you can be better prepared before considering another application. - read more
Quick and Easy Tips to Boost Your Loan Approval Odds Without Affecting Credit
Loan approval can often be a crucial milestone in achieving your financial goals. Whether you're looking to buy a home, pay for education, or consolidate debt, securing a loan can provide the financial boost you need to move forward. - read more
Steps to Take Immediately During a Financial Crisis: A Credit-Friendly Approach
A financial crisis can come in many forms, such as a job loss, unexpected medical bills, or an economic downturn. These events can drastically alter your financial stability and may lead to financial distress. - read more
Understanding Your Credit File: How to Seek Loans without Negative Impacts
Understanding financial health is paramount when venturing into the realm of loan acquisition. It's the backbone that supports not just your immediate monetary requirements but ensures longevity in your fiscal stability. At the heart of this understanding lies a critical aspect: the credit score. It's a numerical representation of your financial trustworthiness, influenced by past fiscal decisions and behaviors. - read more
Choosing the Right Loan for Your Personal Needs in Australia
Choosing the right loan can be a pivotal decision in your personal financial journey. In Australia, where a diverse range of loan options is available, selecting the loan that aligns perfectly with your needs is more crucial than ever. A judicious choice can help you fulfill your dreams—be it buying a new home, investing in education, or consolidating debt—while ensuring that the repayments remain manageable and do not lead to financial strain. - read more

Finance News

Personal Loan Demand Eases as Borrowers Face Higher Rates
11 Nov 2026: Paige Estritori
Australia’s latest lending figures point to a more cautious personal finance market, with new fixed-term personal loan commitments easing in the September quarter as interest-rate pressure continued to shape household decisions. The Australian Bureau of Statistics reported $9.3 billion in seasonally adjusted personal fixed-term commitments for the quarter, down 3.9 per cent from June and slightly below the same period a year earlier. - read more
AI-Drafted Finance Complaints Put Accuracy Back in Focus
04 Nov 2026: Paige Estritori
AFCA’s 2025-26 Annual Review has added a new wrinkle to Australia’s finance complaints landscape: artificial intelligence may help consumers explain a dispute, but poorly checked AI-generated submissions can also make a complaint harder to resolve. For borrowers dealing with personal loans, credit reporting issues or repayment stress, the practical lesson is that accuracy, chronology and evidence still matter more than polished wording. - read more
Broker Review Puts Loan Recommendations Under Fresh Scrutiny
28 Oct 2026: Paige Estritori
ASIC’s latest review of mortgage broker conduct has put a spotlight on how loan recommendations are explained, documented and challenged when a cheaper option is available. Although the review focused on home loan brokers, the practical lesson is broader: borrowers should understand not only the advertised rate, but also why a particular loan structure, lender or feature is being presented as suitable. - read more
Higher Cash Rate Raises the Bar for Loan Affordability
24 Oct 2026: Paige Estritori
The Reserve Bank of Australia's decision on 29 September 2026 to lift the cash rate target by 25 basis points to 4.60 per cent has put loan affordability back in focus for households and small business operators already managing higher everyday costs. While the cash rate does not mechanically set every personal loan or short-term credit price, it influences funding costs, lender risk settings and the way borrowers think about repayment buffers. - read more
Tax Debt Pressure Is Reshaping Small Business Borrowing
16 Sep 2026: Paige Estritori
Small business finance is again in focus as more Australian operators look for ways to manage tax debts, supplier bills and uneven cash flow. Recent finance sector commentary points to a practical shift: lenders are still willing to consider funding requests, but they are looking more closely at whether a business can realistically service new repayments while existing obligations remain under pressure. - read more
Loan Complaints Put Borrower Treatment Back Under the Microscope
09 Sep 2026: Paige Estritori
Fresh financial complaints data has kept Australia’s lending sector under pressure, with consumer credit issues remaining a major concern for households already dealing with higher everyday costs. While the figures cover a broad range of products, the message for borrowers is clear: the way a lender assesses, explains and manages a loan can matter just as much as the advertised rate. - read more
Why Cash-Flow Data Is Changing Loan Assessments
02 Sep 2026: Paige Estritori
Australian lending is continuing to shift towards faster, data-led assessment, with more providers using bank transaction history, income patterns and real-time affordability checks to understand whether a borrower can manage repayments. For people who have been knocked back by a mainstream bank, this is an important development because it can reduce the emphasis on a single credit score and place more weight on what is happening in the borrower’s finances today. - read more
Hardship Support Moves Higher on the Lending Watchlist
26 Aug 2026: Paige Estritori
Australia’s credit sector is facing renewed pressure to treat financial hardship as a core borrower protection, not a back-office process. The latest lending market focus is on how quickly and fairly credit providers respond when customers say they are struggling, especially as household budgets remain stretched by rent, utilities, groceries and existing debt commitments. - read more
Buy Now Pay Later Rules Are Changing for Australian Borrowers
19 Aug 2026: Paige Estritori
Australia's buy now pay later sector is moving into a more regulated era, with providers being brought closer to the consumer credit framework that already applies to many personal loans and credit products. For borrowers, the practical message is simple: short-term convenience is being matched with stronger scrutiny around affordability, hardship support and responsible lending. Find out now if you qualify and compare rates, offers and options from multiple lenders - without a credit check! - read more
Why Personal Loan Pricing Is Still Uneven for Australians
12 Aug 2026: Paige Estritori
Recent personal loan market updates suggest Australian borrowers are seeing more competition in some parts of the lending market, but the benefits are not being shared evenly. Secured borrowers with stable income and strong repayment histories may find sharper advertised rates, while people applying for unsecured loans, short term loans or specialist bad credit loans still face a more complicated pricing picture. - read more


Knowledgebase
Fixed-Rate Mortgage:
A mortgage loan where the interest rate remains the same for the entire term of the loan.


Quick Links: | No Credit Check Loans | Personal Loans No Credit Check | Bad Credit Loans | Business Loans No Credit Check | Loan Information Australia | Unsecured Loans | Loan Eligibility Criteria | Short Term Loans | Emergency Loans | Personal Loan Information