

The Importance of an Emergency Fund: A Guide for Families
Let's dive into the essential topic of emergency funds. An emergency fund is a stash of money set aside to cover the financial surprises life throws your way. These unexpected events can include sudden unplanned repairs, medical emergencies, or job loss. - read more

Maximize Your Loan Options without a Credit Footprint: Strategies to Know
As we navigate the complexities of today's economy, the significance of credit can scarcely be overstated. Whether we're considering a home mortgage, a new car, or managing our personal finances, our credit health often dictates the terms and accessibility of financial support. A robust credit score can open doors to favorable loan terms and rates, while a poor score can narrow our options and cost us more in the long run. - read more

Choosing the Right Loan for Your Personal Needs in Australia
Choosing the right loan can be a pivotal decision in your personal financial journey. In Australia, where a diverse range of loan options is available, selecting the loan that aligns perfectly with your needs is more crucial than ever. A judicious choice can help you fulfill your dreams—be it buying a new home, investing in education, or consolidating debt—while ensuring that the repayments remain manageable and do not lead to financial strain. - read more

Understanding Your Credit File: How to Seek Loans without Negative Impacts
Understanding financial health is paramount when venturing into the realm of loan acquisition. It's the backbone that supports not just your immediate monetary requirements but ensures longevity in your fiscal stability. At the heart of this understanding lies a critical aspect: the credit score. It's a numerical representation of your financial trustworthiness, influenced by past fiscal decisions and behaviors. - read more

Debt Management Tips for Young Adults in Australia
Managing debt early in adult life can make day-to-day money decisions easier and help build a more stable financial foundation. This guide explains practical ways to understand what you owe, create a workable budget, choose a repayment strategy, use credit carefully and know when to seek professional support. - read more

How to Use Credit Cards Wisely to Enhance Your Credit Score
Your credit score is more than just a number; it's a reflection of your financial health. Essentially, it’s a numerical expression that represents your creditworthiness. Lenders use this score to assess the level of risk involved in lending you money. - read more

Loan Hunting with Confidence: How to Check Options Without Credit Damage
Embarking on the journey to secure a loan can feel like navigating a minefield with your credit score as the prize. It's no secret that your credit score is your financial fingerprint, impacting not just your loan prospects but also the terms you're offered. However, the act of loan hunting itself, if not done carefully, can take a toll on this crucial number. - read more

Understanding Your Credit Footprint: Borrowing Strategies to Keep Your Score Intact
Understanding the mechanics behind credit scores is pivotal for anyone navigating the intricate world of finance. A strong credit score does not only unlock the gates to a plethora of borrowing options but also secures favorable interest rates, which can save you a substantial amount of money over time. It acts as a financial passport, one that enables you to achieve milestones such as purchasing a home or car with ease. - read more

Quick and Easy Tips to Boost Your Loan Approval Odds Without Affecting Credit
Loan approval can often be a crucial milestone in achieving your financial goals. Whether you're looking to buy a home, pay for education, or consolidate debt, securing a loan can provide the financial boost you need to move forward. - read more
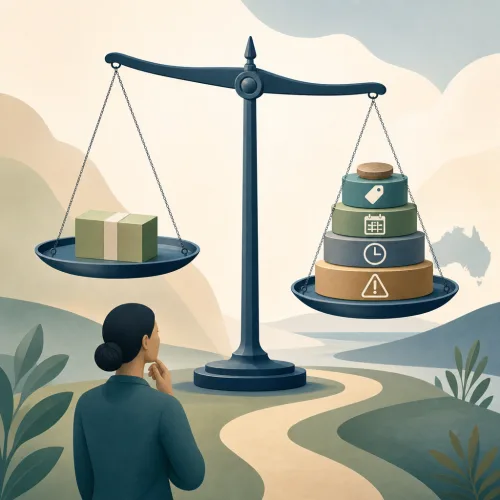
Costs and Fees to Understand Before Taking a No-Credit-Check Loan
Before applying for a no-credit-check or short-term loan, Australian borrowers should understand the total repayment cost, not just the amount borrowed. This guide explains common fees, interest, repayment frequency, loan terms and risk factors to compare. - read more
No comments yet. Be the first to share your thoughts.